Innovation comes not from a magic wand or mouthing some gibberish. It comes from critical thinking and applying out-of-home methods that work. Two nations, Kenya and Ghana, have proved that this is true with the way the two countries have redefined regulations and innovated consumer lending.
Has Ghana blazed a trail in innovative regulation? Under the new Director General of the National Communications Authority, Reverend Edmund Fianko, Ghana’s telecom regulator has turned the rulebook on its head. The country has jettisoned the well-worn path, and it is blazing a trail. It has changed the strategy for shepherding the flock. Ghana is no longer imposing fines on erring telecom operators that may have delivered subpar service. That was in its past. Instead, the Ghana telecom regulator has asked the erring operators to build masts, towers, antennas and upgrade infrastructure.
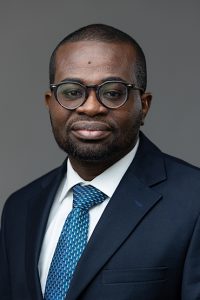
The regulator has said it would not slap a hefty fine on an erring operator and then keep the money. This was the practice in the early days. The former practice [of keeping the money in the coffers] had only benefited a few private pockets. It did not benefit the economy, telecom subscribers, or the operators.
Ghana’s communications regulator has pointed to the stark result of the former behaviour, which is the paucity of telecom infrastructure in that country. This experience is so evident that in the last five years, only 200 towers have been built. The result is a lack of telecom towers, poor telecom services, occasioned by dropped calls, poor reception, etc. The question is, will this innovative regulation ensure the obesity of telecom infrastructure?
Good thinking, Ghana.
Kenya takes the wind out of the sails of debtors in a new crackdown. The Central Bank of Kenya [CBK] and the Sacco Societies Regulatory Authority have introduced new consumer protection rules that would stop lenders from automatically increasing credit limits. To fill the void, the regulator would have to check whether the user could afford more debt. It would obtain the user’s information by reviewing a user’s income, expenses, existing loans and assets before offering any additional credit.
CBK is not only regulating lenders’ behaviour. It is working to fix the decision-making upfront. That means forcing fintechs to rethink growth strategies built on easy, automated credit expansion. Whether these rules can be enforced across a fast-moving, tech-driven sector is a different kettle of fish.
Thumbs up to CBK